Dangote Cement Shelves London Listing, Recalibrates Global Capital-Markets Strategy
Strong Nine-Month Profits Failed to Offset Weak Listing Conditions
Dangote’s East African Gambit: Buying Into Kenya’s Pipeline for $327 Million
Business Marketing Strategies Branding Mining Energy Management Management Consulting Stock Markets Advertising Entrepreneurship Etiquette FrizeMedia Small Business Advice Dropship Business Career Planning Business Marketing Health Food and Drink Communications Beverages Parenting
Malawi Delegation Studies Ghana’s Gold-Sector Reforms at GoldBod
Dangote Cement Shelves London Listing Plan, Recalibrates International Capital-Market Strategy
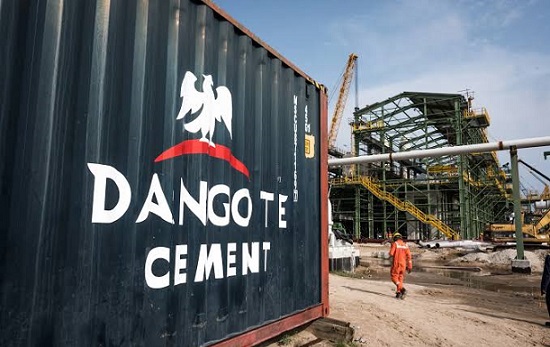
Dangote Cement Plc has decided to discontinue, effective immediately, its proposed secondary listing and share offering on the London Stock Exchange.
The move marks a significant strategic recalibration of the company’s international capital-market ambitions. The decision reflects financial discipline: it is a withdrawal from a proposed route to international market access, not a deterioration in the company’s underlying business or a delisting from its existing Nigerian Exchange platform.
Following a November 10, 2026 decision by its Board, Dangote Cement and its controlling shareholder, Dangote Industries Limited, chose to discontinue the proposed London transaction, citing prevailing market conditions and strategic priorities.
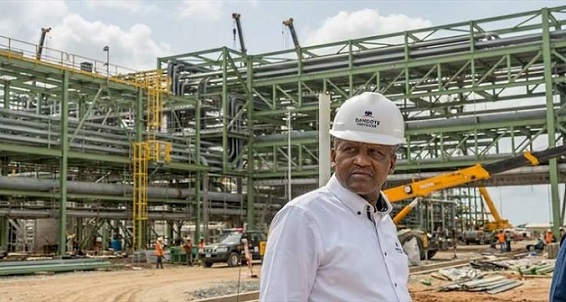
The decision effectively suspends an initiative designed to broaden international ownership, improve access for global investors, and potentially enhance the company’s valuation visibility among institutional investors. Its immediate market implications are therefore more nuanced than those of a conventional negative corporate announcement. According to Reuters’ November 10 report, Dangote Cement’s market valuation stands at approximately N24.79 trillion, or $18.42 billion, making it one of Africa’s most significant publicly traded industrial enterprises.
Cancelling the proposed London listing does not, by itself, eliminate that valuation, impair the company’s productive assets, or change its earnings-generating capacity. It merely removes a potential international pricing and liquidity mechanism that could have broadened the pool of investors able to participate in the company’s equity.
It is important to distinguish between market capitalisation and realised corporate value. Market capitalisation is the prevailing share price multiplied by the number of outstanding shares; it is not cash held by the company, nor does it automatically rise or fall simply because a secondary listing has been abandoned.
The key investment question is therefore not whether Dangote Cement has lost a London listing premium, but whether its earnings, cash flows, production capacity, dividend potential, and expansion strategy continue to justify its market valuation. The proposed London transaction was designed to broaden Dangote Cement’s international investor base. Its abandonment underscores how critical market timing is in large cross-border equity transactions.
International listings are not simply prestige projects. They require careful consideration of liquidity, investor appetite, foreign-exchange exposure, regulatory obligations, transaction costs, and the ability to achieve an attractive valuation.
When prevailing market conditions erode these anticipated benefits, postponing or abandoning a transaction can be a rational exercise in capital-market management rather than a sign of corporate weakness. For Dangote Cement, preserving its existing market position while avoiding an unfavourable international transaction may ultimately prove more prudent than pursuing a listing at a valuation, or under conditions, that fail to maximise shareholder interests.
The development also has implications beyond Dangote Cement. For the Nigerian capital market, retaining a company of this scale on the domestic exchange reinforces the strategic importance of deepening local liquidity, strengthening institutional participation, and attracting long-term domestic and foreign investment. For London, the abandoned transaction represents a missed opportunity to attract a prominent African industrial issuer at a time when international exchanges are competing for major listings.
Nevertheless, the absence of a London secondary listing does not diminish Dangote Cement’s international commercial relevance. Its operating footprint, industrial infrastructure, and position within Africa’s construction-materials value chain remain more substantive indicators of its economic significance. The decision to discontinue its proposed London Stock Exchange listing should therefore be viewed as a strategic adjustment to current market realities, not as an automatic negative reassessment of its corporate fundamentals.
With an estimated market capitalisation of $18.42 billion, the company remains a major African industrial asset. Over the long term, its equity investment case will hinge on earnings quality, operating efficiency, capital allocation, production growth, dividend capacity, and its ability to translate Africa’s infrastructure and urbanisation needs into sustainable shareholder returns.
Although the London listing opportunity has been withdrawn, the underlying industrial investment case remains intact. For investors, this distinction is critical: cancelling a listing does not cancel the business strategy, and the absence of an international quotation does not prove that intrinsic value has diminished.
Another exchange listing is not necessarily the next decisive catalyst for valuation. The real catalyst will be Dangote Cement’s ability to show that its operating performance, financial discipline, and expansion ambitions can consistently generate returns commensurate with its substantial market valuation. In brief, it is a strategic withdrawal from an international listing, an ongoing commitment to the core industrial business, and a fresh test of whether valuation is supported by fundamentals.
Tweet